DSCR Loans
Long-Term Rental Loans Built on Cash Flow
Finance your rental property on the income it produces, not your personal income. Our DSCR loans offer long-term fixed and adjustable options for purchases, refinances and cash-out, with no tax returns or W-2s required. We originate, underwrite and close every loan in-house.
Program Highlights
- Loan Size
- $100K–$3.5M
- Time to Close
- 14 to 30 days
- Interest Rate
- Starts at 6.25%
- Term
- Up to 40 years
- LTV
- Up to 80%
Don't see what you need?
Call us at +1 (917) 734-2530 or email us at financing@malajcapital.com
How Our DSCR Loans Work
- Qualify on rents, not personal income
- No tax returns or W-2s required
- Purchase, refinance and cash-out
- Up to 40 years, fixed-rate or ARM
- Interest-only periods available
- Long-term and short-term rentals
Why Investors Choose Our DSCR Loans
Built for rental investors and the brokers who serve them
Fast Funding
Tailored Solutions
Competitive Rates
Expert Team
Eligible Property Types
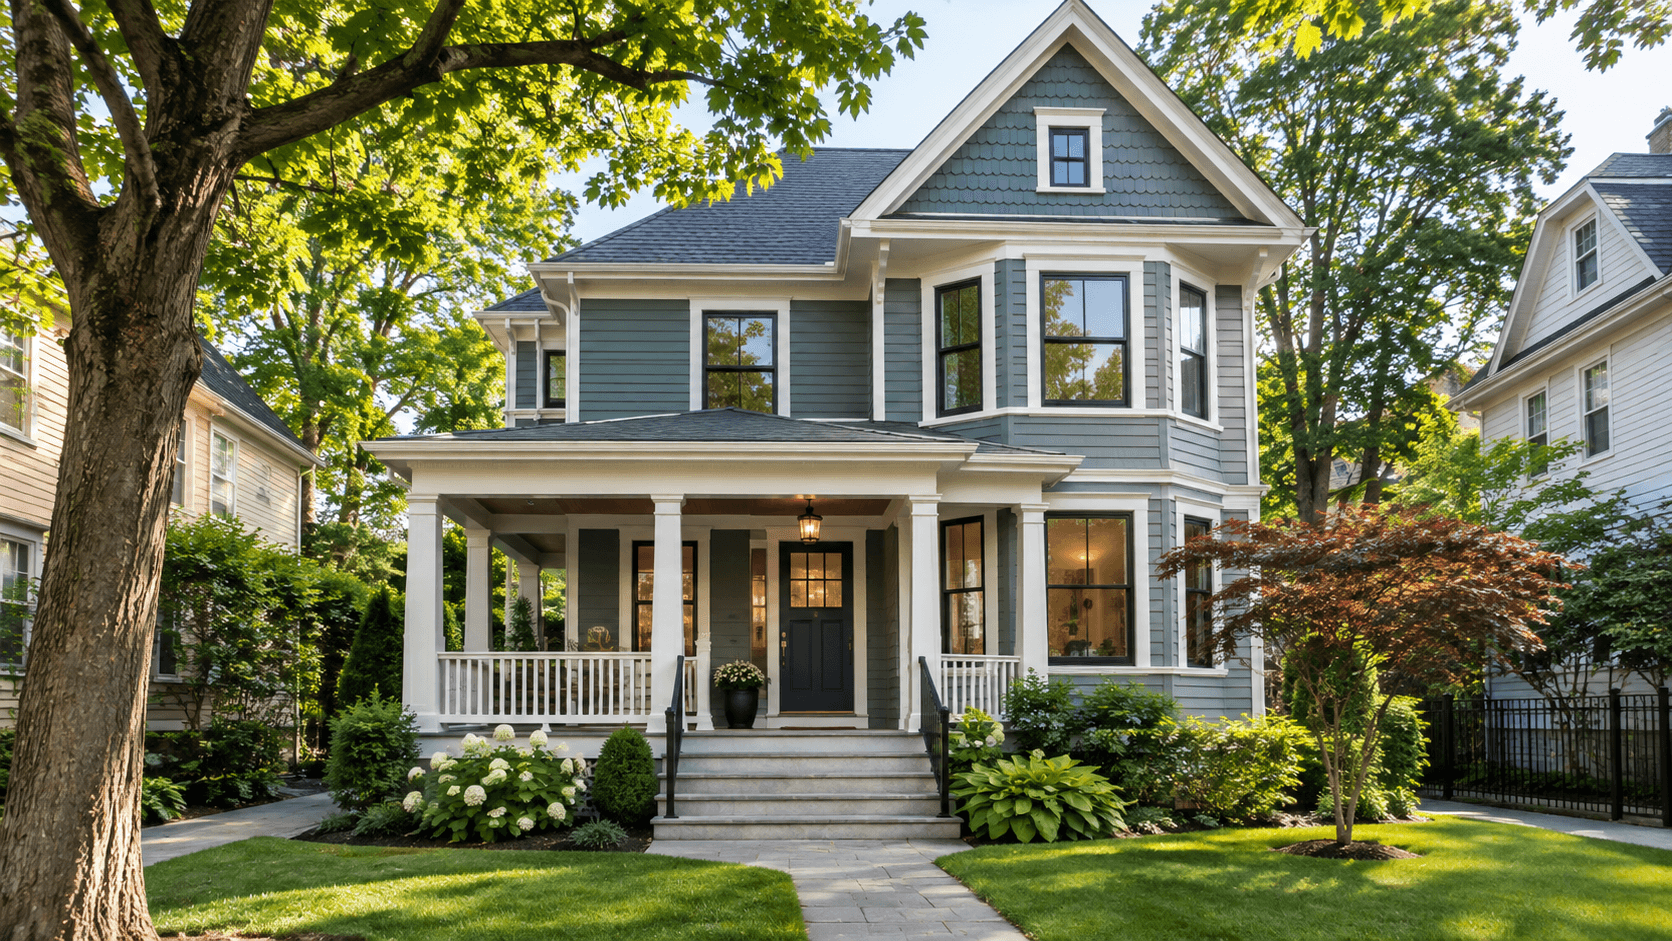
Single-Family & Townhomes
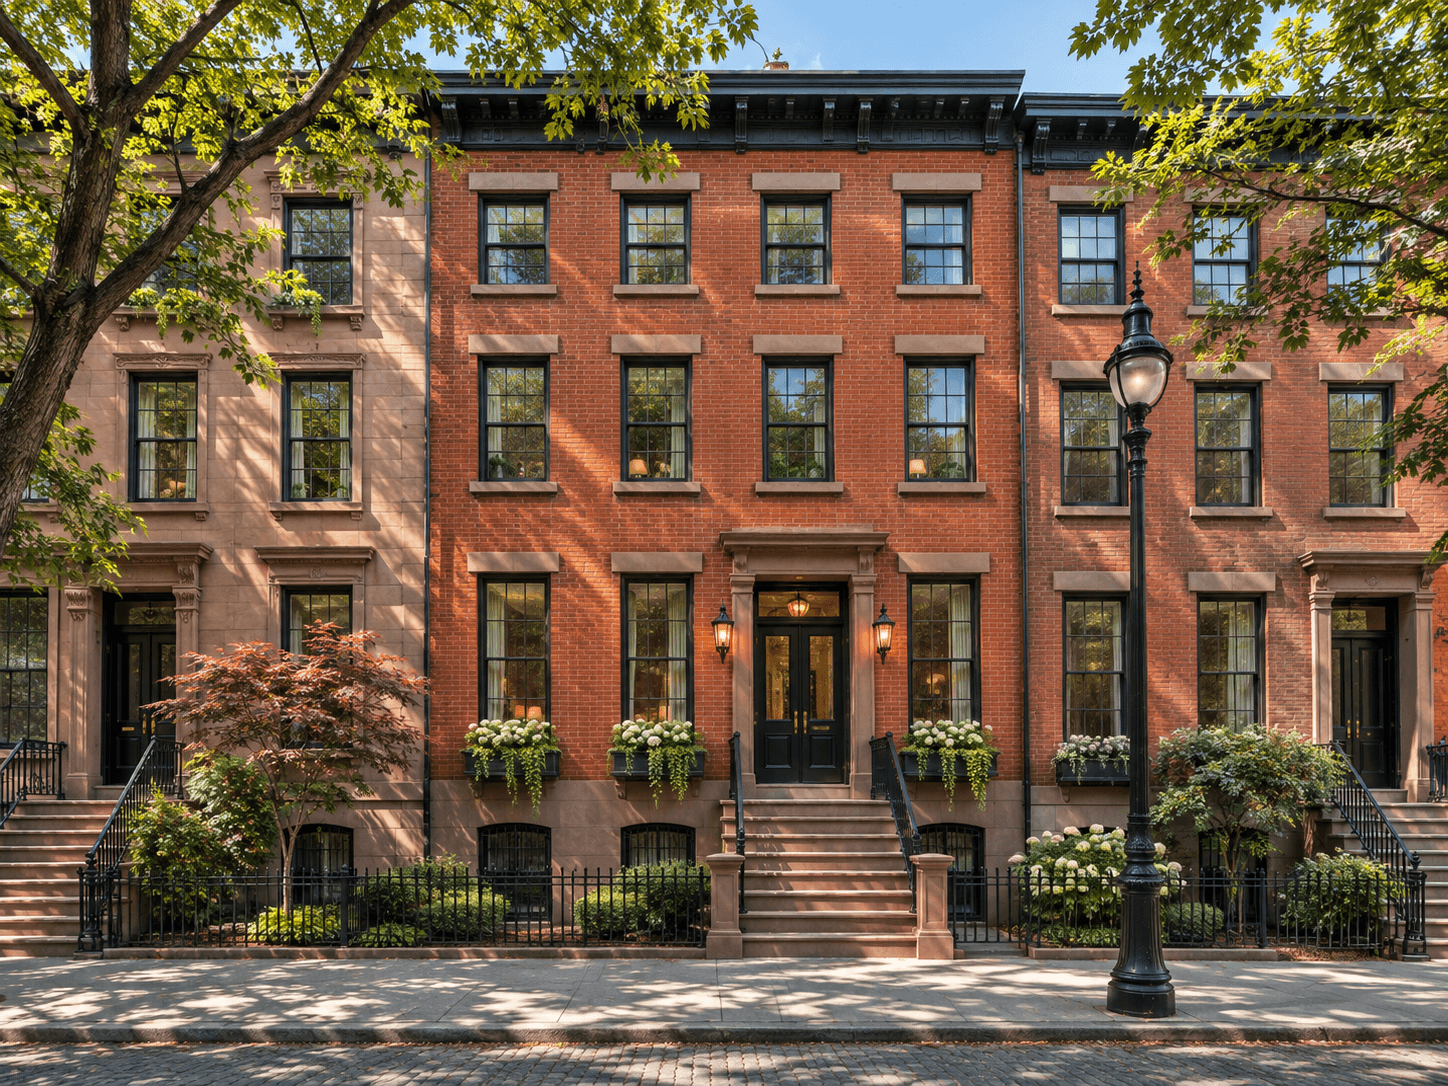
2–4 Unit Homes
Condos & PUDs
Small Apartment & Mixed-Use

Frequently Asked Questions
What is a DSCR loan?
A long-term rental loan qualified on the property’s debt service coverage ratio, meaning its rental income compared to the monthly mortgage payment, rather than your personal income.
How much can I borrow?
Loans range from $100K to $3.5M, up to 80% of value on purchases and 75% on refinances. Leverage depends on DSCR, credit and loan size.
What DSCR do I need?
Most loans qualify at a DSCR of 1.0 or higher. Properties below 1.0 can still qualify at lower leverage, and stronger coverage unlocks better pricing.
What are your loan terms?
Choose fixed or adjustable-rate terms up to 40 years, with interest-only periods available. Rates start at 6.25% and depend on leverage, DSCR and credit.
How fast can you close?
Most DSCR loans close in 14 to 30 days, depending on appraisal, title and how quickly documents come in.
Can first-time investors qualify?
Yes. First-time investors are eligible on single-unit properties with strong credit and a DSCR above 1.0.
Can I refinance out of a bridge loan?
Yes. Many of our fix-and-flip and bridge borrowers refinance into a DSCR loan once the property is renovated and rented, keeping the project with one lender.
Explore residential bridge loansWhat credit score do I need?
Credit requirements vary by program, and we have options for a wide range of credit profiles. Stronger credit and DSCR unlock higher leverage and better pricing.
What do I need to apply?
A purchase contract or current mortgage statement, executed leases for refinances (short-term rentals use 12 months of rental history), entity documents, a credit authorization, bank statements showing reserves and a signed business purpose certification.
Can’t find what you need?
Our team is here to help. Contact us with your question or deal details, and a senior member of our team will get back to you promptly.
Contact our teamHave a property or project in mind?
Talk with our team about the property, business plan and capital need. We’ll help you identify the right next step.